GSTR-3B Explained with Practical Examples
GSTR-3B is your monthly GST summary and payment return. Understand its tables, the 2025 liability lock, ITC and RCM, set-off order and a worked rupee example.
Quick answer
GSTR-3B is the summary return in which a GST-registered business declares its output tax, claims input tax credit (ITC) and pays the difference. Monthly filers file by the 20th of the following month; QRMP filers file quarterly by the 22nd or 24th, depending on their state. Since the July 2025 tax period, the sales liability that flows in from GSTR-1 cannot be edited in GSTR-3B.
What GSTR-3B does
Think of it as your GST cheque for the period. It answers three questions:
- How much tax did you charge on sales (output tax)?
- How much tax did you pay on eligible purchases (input tax credit)?
- What is the difference you must pay in cash?
The main tables in plain language
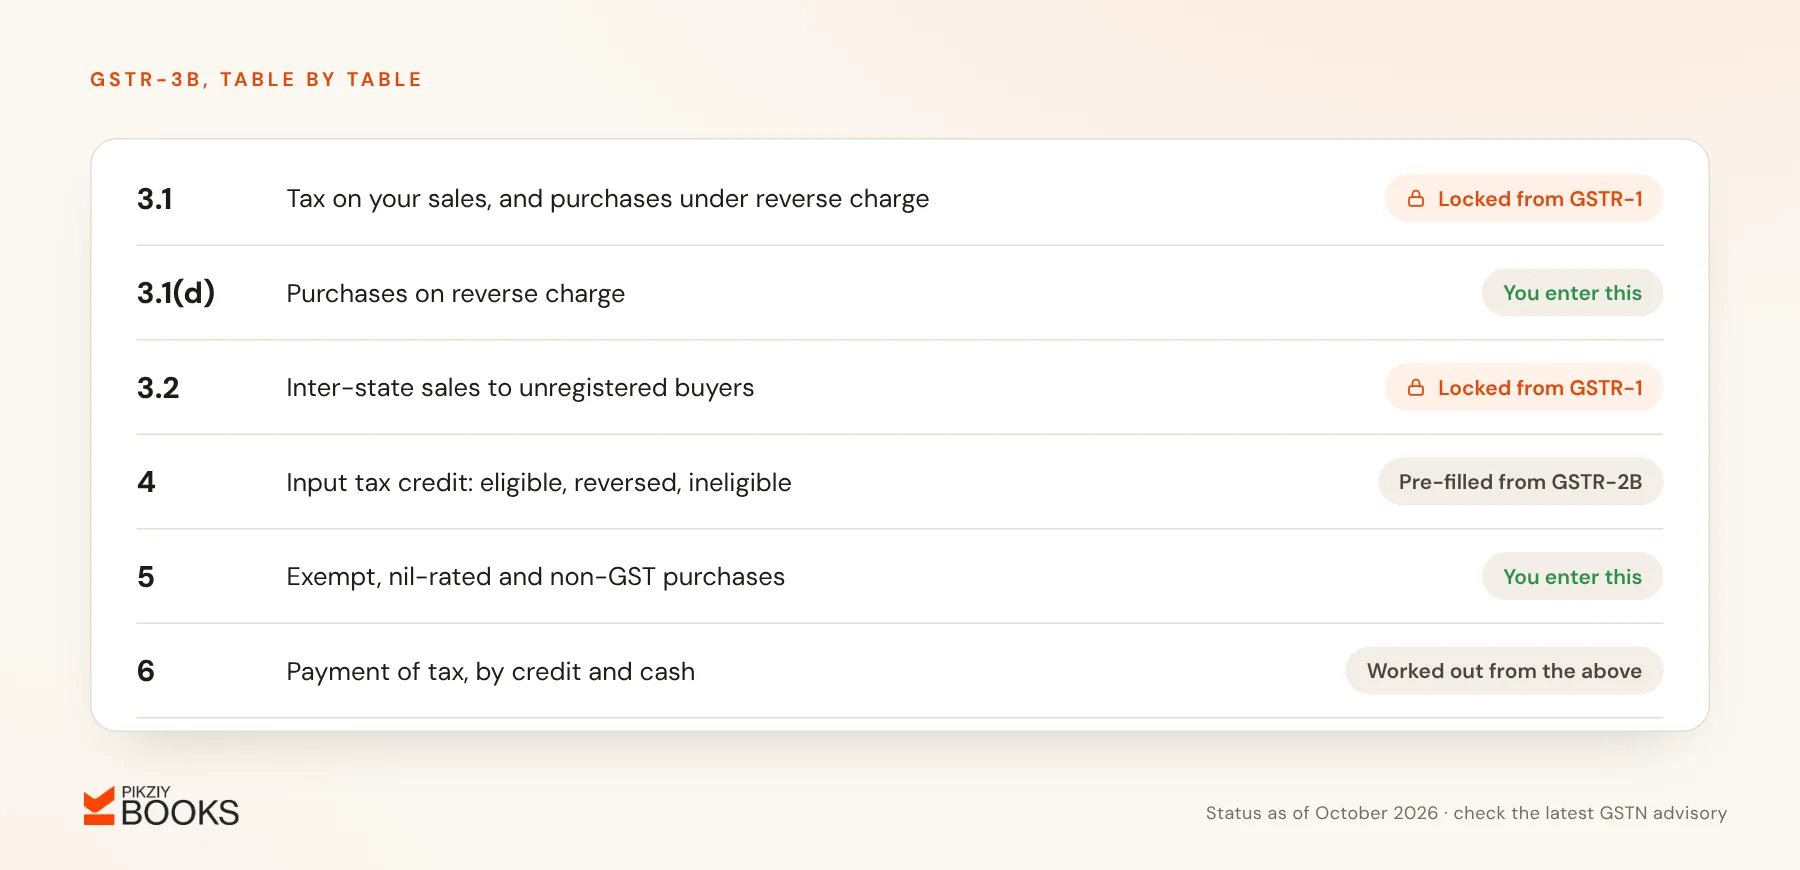
| Table | What it holds | Where the figures come from |
|---|---|---|
| 3.1 | Tax on your sales, and on purchases under reverse charge (3.1(d)) | Sales: locked from GSTR-1/1A/IFF. Reverse charge: entered by you |
| 3.2 | Inter-state sales to unregistered buyers, composition dealers and UIN holders | Locked from GSTR-1 |
| 4 | Eligible ITC, ITC reversed and ineligible ITC | Pre-filled from GSTR-2B |
| 5 | Exempt, nil-rated and non-GST purchases | Entered by you |
| 6 | Payment of tax, using credit and cash | Worked out from the above |
The lock on liability
GSTR-3B is pre-filled: your liability comes from GSTR-1 (or GSTR-1A and IFF), and your credit from GSTR-2B, based on what you accepted or left pending in the Invoice Management System (IMS). Since the July 2025 tax period, the sales liability in Table 3.1 is locked, and since the November 2025 period, Table 3.2 is locked too. If a figure is wrong, you correct it through GSTR-1A before filing GSTR-3B.
ITC in Table 4 has been auto-populated from GSTR-2B since late 2025. A similar lock on ITC has been expected for some time; at the time of writing, check the latest GSTN advisory on the portal before you file.
Worked example
Kavya Interiors in Bengaluru (Karnataka) has the following for November.
| Output tax | Taxable value | Tax |
|---|---|---|
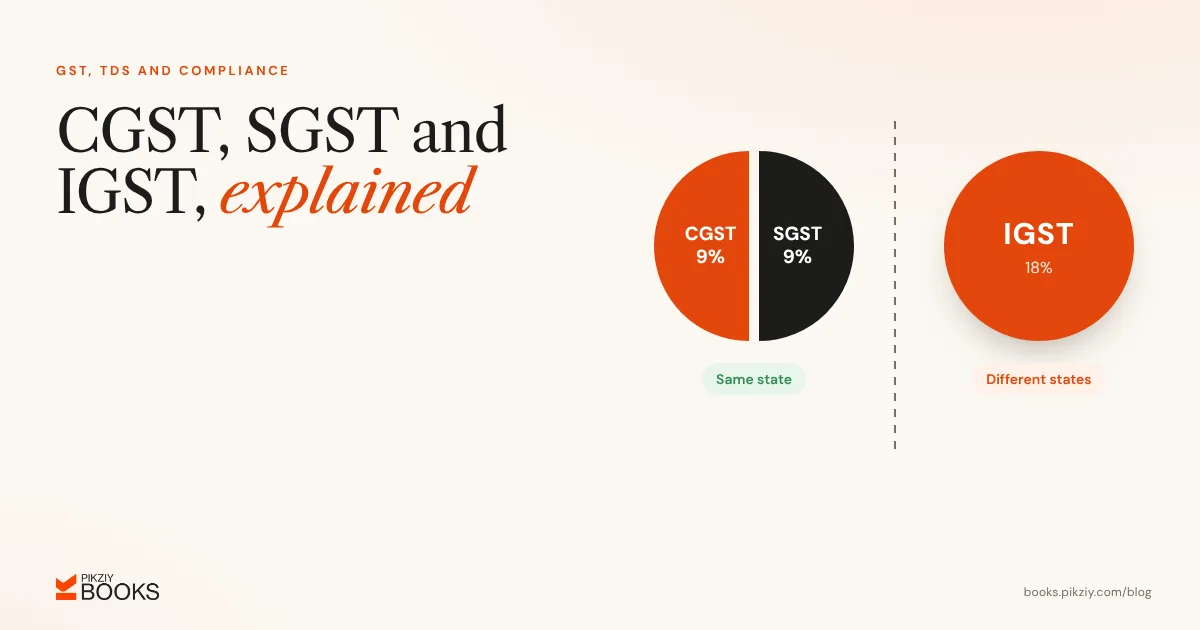
| Services within Karnataka | ₹4,00,000 | CGST ₹36,000 + SGST ₹36,000 |
| Services to clients in other states | ₹1,50,000 | IGST ₹27,000 |
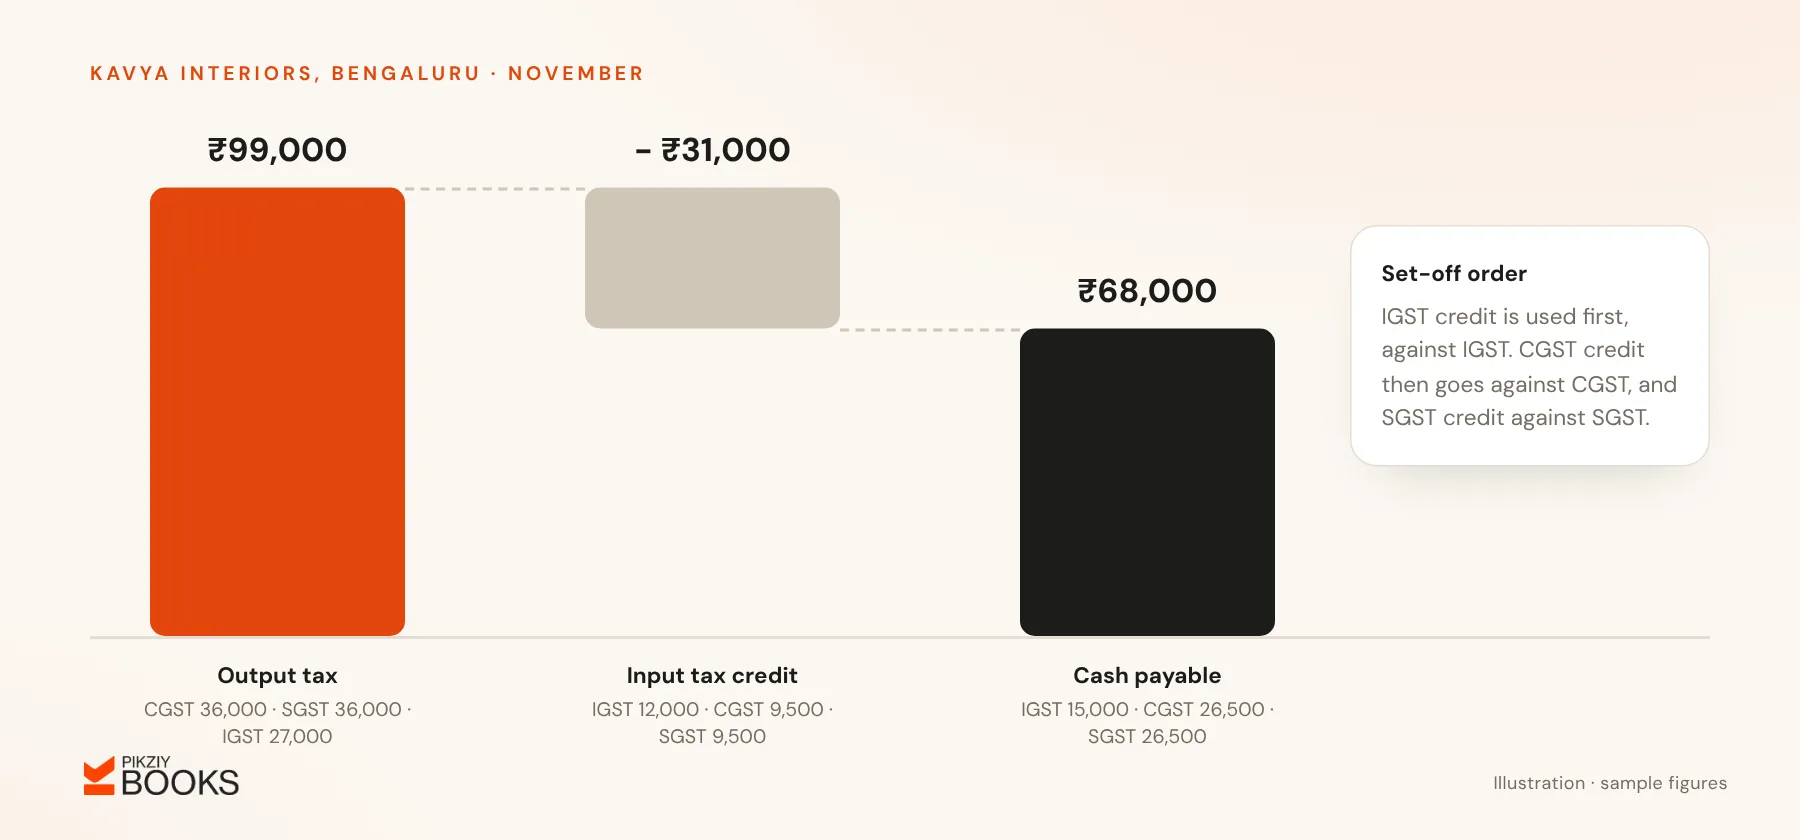
| Total output tax | ₹99,000 |
| Eligible ITC (from GSTR-2B) | Tax |
|---|---|
| Furniture bought from Maharashtra for client projects | IGST ₹12,000 |
| Local purchases and software subscriptions | CGST ₹9,500 + SGST ₹9,500 |
| Total ITC | ₹31,000 |
Set-off, using the order the law requires:
- IGST credit of ₹12,000 goes first against IGST of ₹27,000. IGST left to pay: ₹15,000.
- CGST credit of ₹9,500 against CGST of ₹36,000. CGST to pay: ₹26,500.
- SGST credit of ₹9,500 against SGST of ₹36,000. SGST to pay: ₹26,500.
Cash payable: ₹68,000 (₹15,000 IGST + ₹26,500 CGST + ₹26,500 SGST), which is ₹99,000 − ₹31,000.
Reverse charge
If you received services under reverse charge, such as legal services from an advocate or transport from a goods transport agency, report them in Table 3.1(d) and pay that tax in cash. You cannot pay reverse charge tax with credit. You can then claim it as ITC in Table 4 if it is eligible.
Due dates, late fees and interest
- Monthly: 20th of the following month.
- QRMP: 22nd or 24th of the month after the quarter, depending on your state. Tax for the first two months is paid by the 25th of the next month using form PMT-06.
- Late fee: charged for each day of delay, lower for nil returns, up to a cap based on turnover.
- Interest: 18% a year on tax paid late, worked out on the portion paid in cash, from the day after the due date.
- Three-year limit: GSTR-3B can no longer be filed once three years have passed from its due date.
A monthly GSTR-3B checklist
- File GSTR-1 (or IFF) correctly first; see GSTR-1 explained.
- Review supplier invoices in IMS and reconcile purchases with GSTR-2B.
- Reverse ineligible and blocked credits; see input tax credit.
- Check reverse charge entries.
- Review the system-generated GSTR-3B, pay the cash due, then file.
Common mistakes
- Filing GSTR-1 with errors and then being unable to fix the liability in GSTR-3B.
- Claiming ITC that is not in GSTR-2B.
- Trying to pay reverse charge tax with credit.
- Leaving interest unpaid on tax paid late.
Frequently asked questions
Can I revise GSTR-3B?
What if I had no sales and no purchases?
Is ITC also locked in GSTR-3B?
Does interest apply to the whole tax or only the cash part?
Next step
Work through the checklist above a few days before the 20th each month. PikZiy Books keeps your sales and purchase records ready for review, so the figures you file in GSTR-1 and GSTR-3B match your books.