Credit that isn't in 2B
A bill in your books, but your supplier hasn't filed it. The credit is claimed anyway and reversed later, with interest.
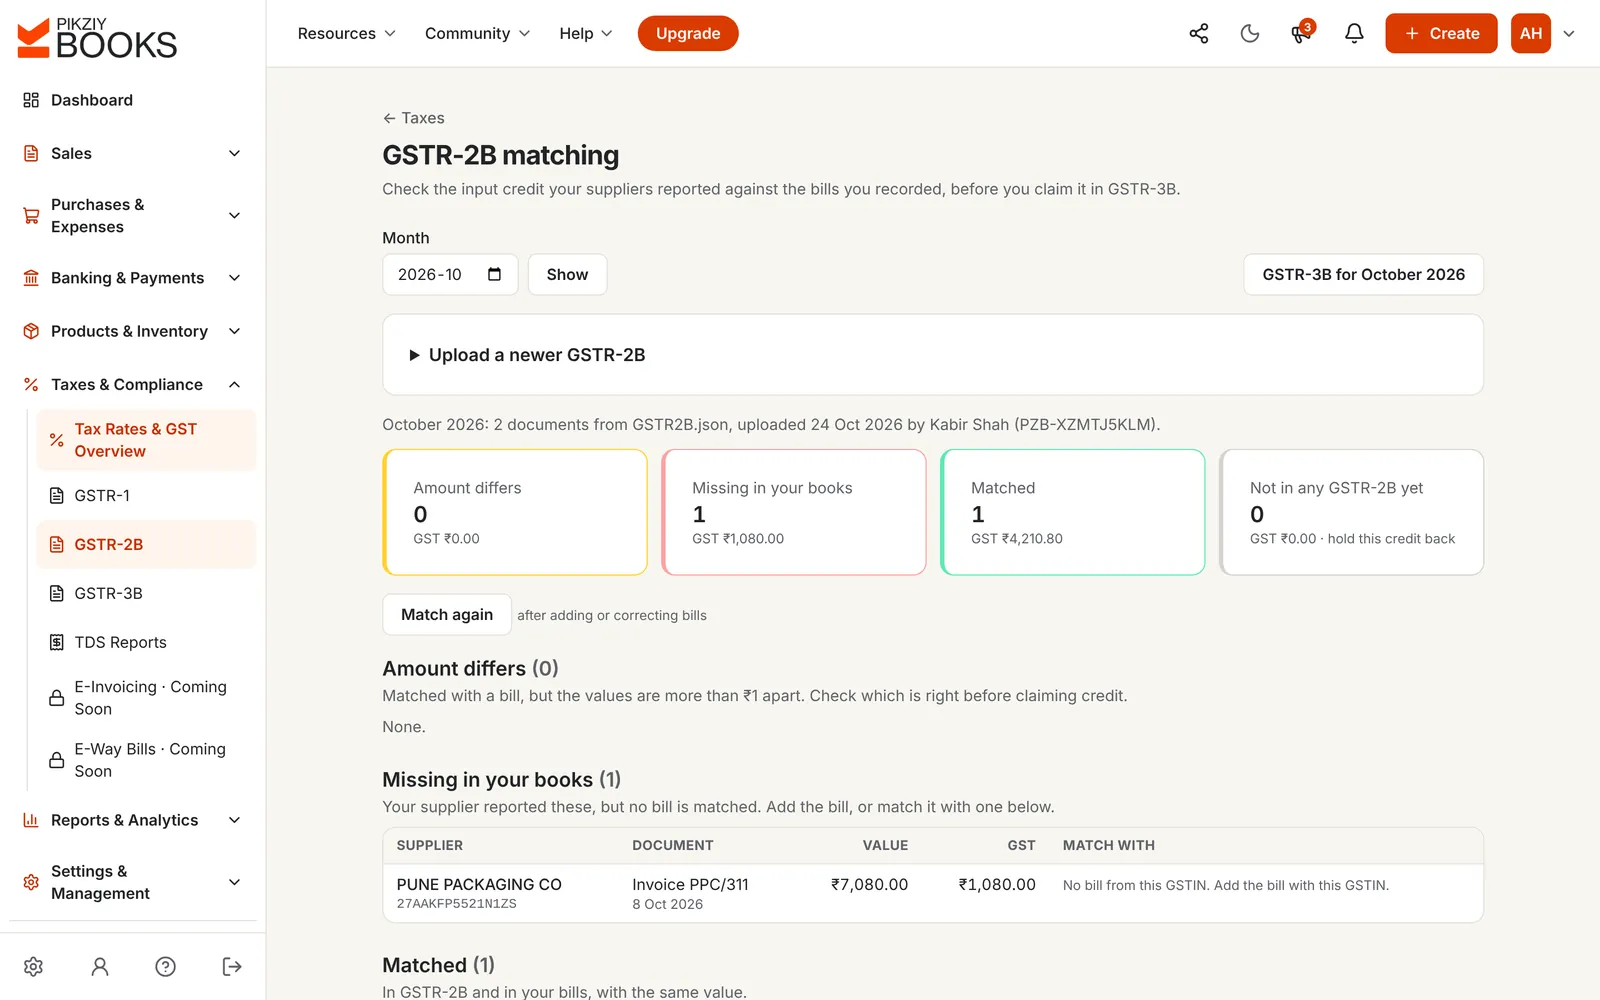
₹1,080 claimed that GSTR-2B never showed.
Tax on your sales, input credit checked against GSTR-2B, reverse charge flagged for review, and the credit set off in the order the law sets, box by box, with the cash to pay. You file on the portal with the figures in front of you.
Sign-ups open November 2026 · 14-day free trial · No card needed to start · GST returns are on the Growth plan and above.
GSTR-3B preparation software works out the monthly summary return from your records: the tax on your sales, the input tax credit you can claim, and the cash left to pay once the credit is used.
PikZiy Books builds it from the same invoices and bills as your GSTR-1, and checks the credit against GSTR-2B first.
A bill in your books, but your supplier hasn't filed it. The credit is claimed anyway and reversed later, with interest.
₹1,080 claimed that GSTR-2B never showed.
IGST credit left unused while central and state tax is paid in cash, or CGST credit used against SGST.
₹2,500 paid in cash that credit should have covered.
Sales in 3.1 typed from a different report than GSTR-1. The portal shows the difference.
A mismatch notice months later.
Screenshots of the real app with a sample shop, Anvi Home Store in Pune.
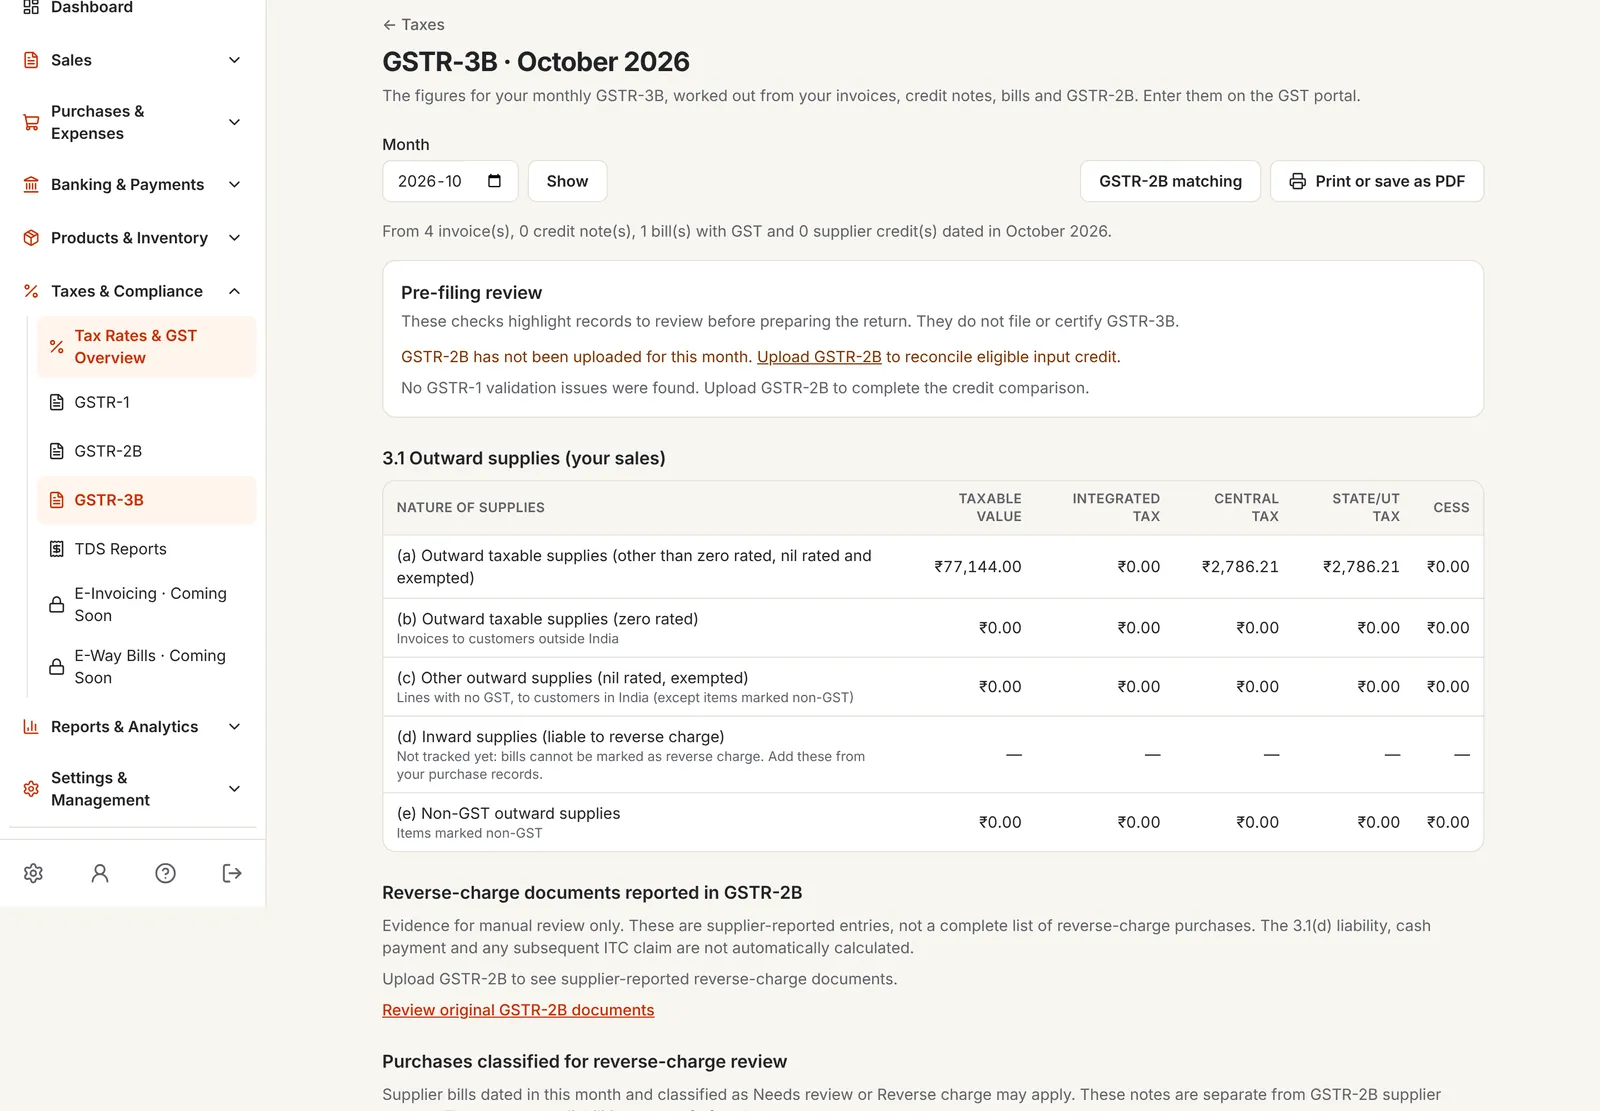
Table 3.1 from the month's invoices and credit notes: taxable, zero-rated exports, nil-rated and exempt, and non-GST, with integrated, central and state tax. Table 3.2 lists inter-state sales to unregistered customers by state.
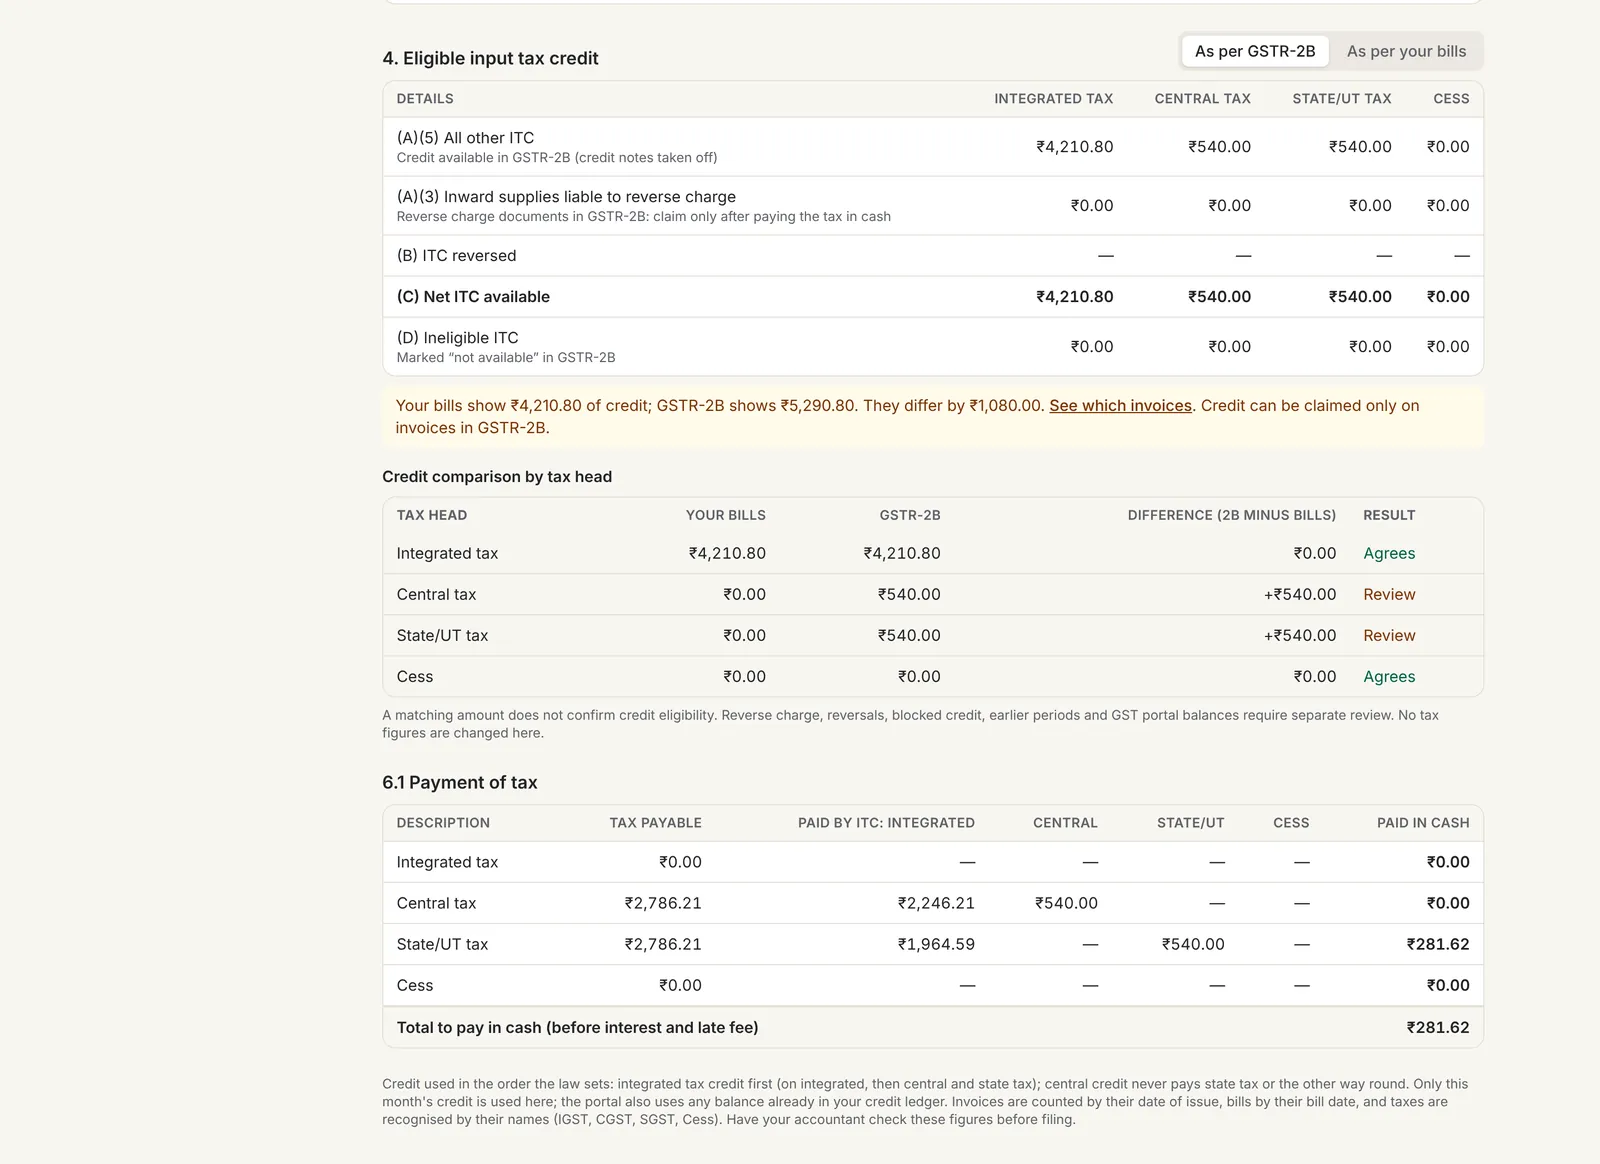
Upload the month's GSTR-2B. Supplier invoices are matched with your bills, and table 4 takes credit as per 2B, with credit notes off and “not available” lines apart.
Reverse-charge documents in GSTR-2B are listed, supplier bills can be classified for review, and the two are cross-checked, so nothing is missed when you work out 3.1(d) with your CA.
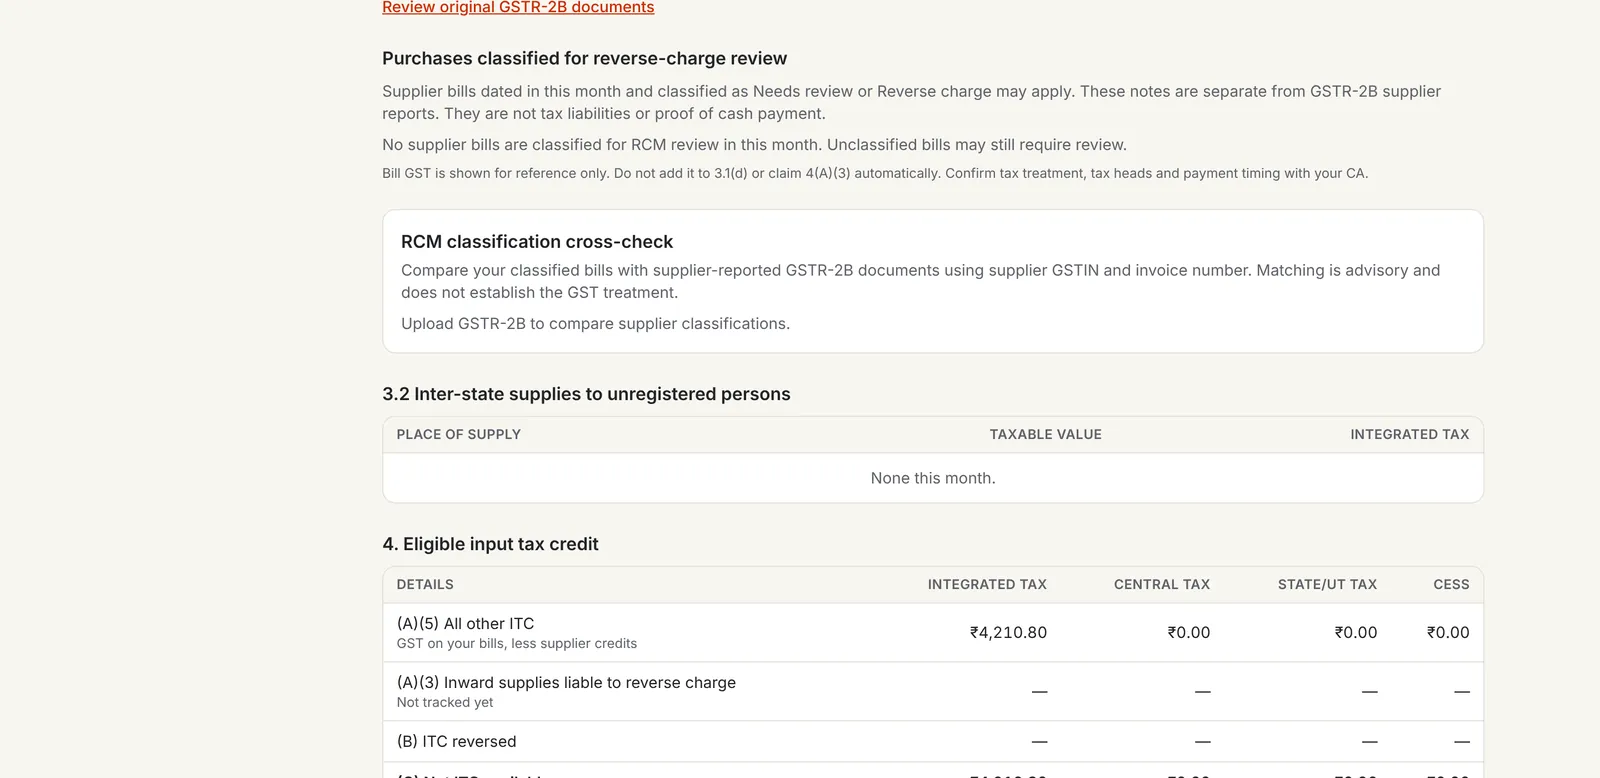
Table 6.1 uses the credit in the order the law sets and shows the cash to pay for each tax, and any credit left to carry forward.
Enter the month's tax on sales and the input credit you can claim, by tax head. See how the credit is used, in the order the law sets, and the cash left to pay.
₹281.62
| Tax | IGST credit | CGST credit | SGST credit | Cash |
|---|---|---|---|---|
| Integrated | — | — | — | — |
| Central | ₹2,246.21 | ₹540.00 | — | — |
| State/UT | ₹1,964.59 | — | ₹540.00 | ₹281.62 |
The same set-off PikZiy Books uses in its GSTR-3B worksheet: IGST credit first, on IGST and then where CGST or SGST credit falls short; CGST and SGST credit never pay each other. Interest and late fee are not included. Nothing you type is saved.
Understand the return: GSTR-3B explained and input tax credit and blocked credits.
| Spreadsheet | PikZiy Books | |
|---|---|---|
| Output tax | From a sales report | From the same records as GSTR-1 |
| Input credit | From the purchase register | As per GSTR-2B, compared with bills |
| Missing supplier invoices | Found in a notice | Listed before you claim |
| Set-off | Worked out by hand | In the legal order |
| Reverse charge | Remembered, or not | Flagged for review |
| Record | A file on someone's laptop | Printed or saved as PDF |
Taxable, zero-rated, nil and exempt, non-GST.
Growth plan and aboveBy place of supply.
Growth plan and aboveAs per GSTR-2B or your bills.
Growth plan and aboveIn the order of section 49 and rule 88A.
Growth plan and aboveUpload the portal's JSON file.
Growth plan and aboveWhat to check before you prepare the return.
Growth plan and aboveYour bills vs 2B by tax head.
Growth plan and aboveFor your records and your CA.
Growth plan and aboveWith GSTINs, so their credit counts.
Business plan and aboveClassify bills and cross-check with 2B.
Business plan and aboveInput and output GST accounts that match.
Business plan and aboveLock the month once filed.
Business plan and aboveGSTR-3B and GSTR-2B matching are on Growth. Supplier bills and reverse-charge review are on Business.
| Feature | Starter | Growth | Business | Enterprise |
|---|---|---|---|---|
| People who can sign in | 1 | 3 | 10 | 20 |
| GST invoices and credit notes | Included | Included | Included | Included |
| GSTR-3B worksheet and GSTR-2B matching | Included | Included | Included | Included |
| Supplier bills for input credit | Not included | Included | Included | Included |
| GST accounts in the books and period locks | Not included | Included | Included | Included |
Every plan has unlimited invoices, customers and items, and starts with a 14-day free trial. Prices are on the plans page, paid monthly or yearly. Businesses that sign up from 1 November 2026 to 30 April 2027 and pay for a year get 18 months for the price of 12. Compare every feature
Software that works out the month's GSTR-3B from your records: tax on sales in table 3.1, inter-state sales to unregistered customers in 3.2, input tax credit in table 4, and how much tax to pay in cash after using the credit, in 6.1. Good GSTR-3B software checks the credit against GSTR-2B before you claim it.
From the month's issued invoices and credit notes by issue date, supplier bills and credits by bill date, and the month's GSTR-2B if you upload it. Each box of the return is shown with its figures, ready to copy into the portal.
Yes, once you upload the month's GSTR-2B: credit is taken as per 2B, with credit notes taken off and reverse charge and “not available” lines shown apart. A comparison by tax head shows where your bills and 2B differ, and you can switch to the bills basis to compare.
The order the law sets: integrated tax credit first, on integrated tax and then on central and state tax; central credit on central tax and then integrated; state credit on state tax and then integrated. Central and state credit never pay each other. The calculator on this page uses the same code.
Partly. Reverse-charge documents in your GSTR-2B are listed, supplier bills can be classified for reverse-charge review, and the two are cross-checked. The reverse-charge liability in 3.1(d), and the credit for it, are not calculated for you; work them out with your CA.
No. The cash to pay is before interest and late fee, and doesn't include balances already in your electronic credit or cash ledger on the portal.
Expenses don't carry the supplier's GSTIN, so their GST isn't counted as credit; the worksheet says how much was left out. Record purchases you claim credit on as supplier bills with the supplier's GSTIN, on Business.
Yes. Print it or save it as a PDF for your records or your CA.
No. It prepares the figures; you or your CA enter them on the GST portal and pay the tax there.
GSTR-3B and GSTR-2B matching are on Growth and above. Supplier bills, which give the credit, and reverse-charge review are on Business.
PikZiy Books opens for sign-ups in November 2026. Join the waitlist and we will tell you the day you can start.
Join the waitlist